Expert Insights from Mandy Green, Licensed Insurance Advisor at MetzWood Insurance
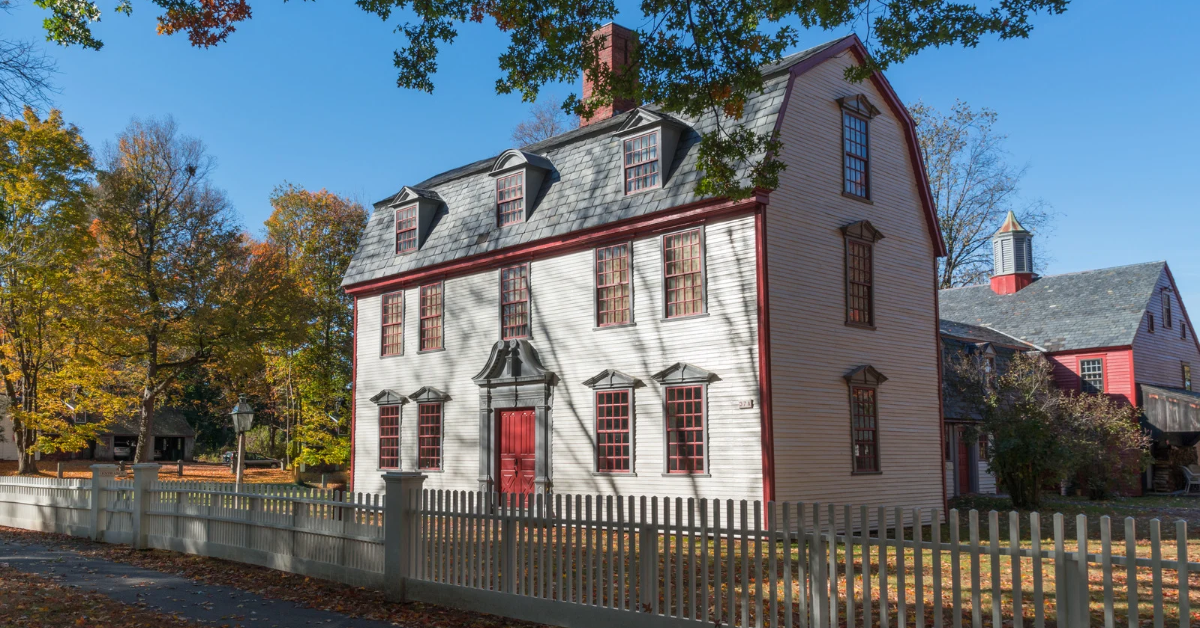
From historic farmhouses to century-old properties, the Hudson Valley is filled with homes offering unique character and architectural charm. But purchasing an older home can also come with insurance challenges that buyers may not anticipate.
We spoke with Mandy Green, Licensed Insurance Advisor at MetzWood Insurance, about what buyers should know before purchasing an older or historic home in the Hudson Valley.
Is It Harder or More Expensive to Insure an Older Home?
Older homes are generally more expensive to insure than newer properties because aging systems, outdated materials and specialized construction can increase the risk of damage and cost of repairs.
According to Green, insurers may also have stricter underwriting requirements, making it important to speak with an insurance agent early, ideally before you're under contract.
How you plan to use the home matters, too. Second homes, seasonal residences and short-term rentals may require additional precautions, such as central station alarms, winterization procedures or a local caretaker.
How Do Aging Roofs and Outdated Systems Affect Homeowners Insurance?
A home's roof, electrical wiring, plumbing and heating systems can significantly affect insurance eligibility and coverage.
- Roofs: Asphalt roofs older than 15 to 20 years may face additional scrutiny. Some insurers may limit coverage to actual cash value rather than replacement cost or require a new roof before issuing a policy.
- Electrical systems: Outdated wiring, including knob-and-tube systems and old fuse boxes, may need to be replaced to qualify for coverage.
- Plumbing and heating: Aging pipes and older heating systems, particularly oil systems, can raise concerns about water damage and other risks.
- Replacement costs: Historic features, custom woodwork and antique finishes may require specialized materials and labor, increasing rebuilding costs.
Green recommends reviewing the home's inspection report and sharing details about these systems with your insurance agent before committing to a purchase.
What Insurance Risks Are Unique to Older Hudson Valley Homes?
The Hudson Valley's geography and seasonal weather create additional considerations for older properties.
Flooding and Water Damage
Homes near the Hudson River or local creeks may face increased flooding risks during heavy rain and severe storms.Even small differences in elevation can affect how water moves across a property.
Hillside Drainage and Foundation Issues
Heavy rainfall and rapid snowmelt can cause runoff that places pressure on aging foundations. Power outages can also disable sump pumps, increasing the risk of basement water damage.
Winter Weather and Ice Dams
Freezing and thawing cycles can create ice dams on older, poorly insulated roofs, allowing moisture to seep beneath shingles and damage interior walls and ceilings.
Standard homeowners insurance policies generally do not cover flooding. Buyers should discuss separate flood insurance with their agent, even if the property is outside a designated high-risk flood zone.
What Additional Insurance Coverage Should Buyers Consider?
Green recommends exploring additional coverage options that can help protect older or historic homes from unexpected expenses.
- Ordinance or Law Coverage: Helps cover the additional cost of bringing a home up to current building codes following a covered loss.
- Extended or Guaranteed Replacement Cost: Provides additional protection when rebuilding expenses exceed the home's insured value, subject to policy terms and limits.
- Water Backup and Sump Pump Coverage: Can help cover damage from backed-up drains, sewers or sump pump failures.
- Flood Insurance: Provides separate protection against flood damage typically excluded from standard homeowners policies.
The right coverage depends on the home's condition, location and unique features.
When Should You Get Homeowners Insurance for an Older Home?
The best time to contact an insurance agent is before you're under contract. An early conversation can help identify coverage restrictions, required repairs or additional insurance needs before closing. Be prepared to share information about the home's age, roof condition, electrical and plumbing systems, heating equipment, renovations and intended use.
Protect Your Hudson Valley Home With MetzWood Insurance
Buying an older home in the Hudson Valley can be a rewarding investment, but understanding its insurance needs is an important part of the process. As MetzWood Insurance Licensed Advisor Mandy Green emphasizes, addressing potential insurance concerns early can help buyers make more informed decisions and avoid surprises.
Planning to purchase an older or historic home in the Hudson Valley? Contact MetzWood Insurance to explore homeowners insurance options tailored to your property.